
SERVICES
Clear answers for your retirement, and someone to see them through.
See what a plan delivers, how it comes together, and what ongoing collaboration looks like.
WHAT A PLAN COVERS
Six core answers that shape your retirement.
01
Your income schedule
Every income source mapped year by year. You see exactly when each stream starts, how much it delivers, and how your cash flow evolves over time.
02
Your spending number
The maximum amount you can sustainably spend each year, clearly divided between your essential living costs and your lifestyle money.
03
Your withdrawal sequence
The exact order and amount to draw from your RRSPs, LIRAs, non-registered accounts and TFSAs, designed to keep your lifetime tax bill as low as reasonably possible.
04
Your CPP and OAS start dates
Specific ages to start each pension, calculated using your own numbers rather than a general rule of thumb, taking the guesswork out of an irreversible decision.
05
What happens to the survivor
How your income and tax brackets change when one spouse is on their own, along with steps to take today so the surviving partner remains financially secure.
06
Your legacy and wealth transfer
A clear framework for transferring wealth efficiently, whether that means giving to family while you're here to see it or reducing the tax impact on your estate down the road.
THE ADVANTAGE PLAN
The complete picture, at a glance.
A good retirement plan should provide answers you can rely on. The Advantage Plan brings together your essential costs and what covers them, your total yearly spending, your withdrawal order, and key risk factors with recommendations for each one.
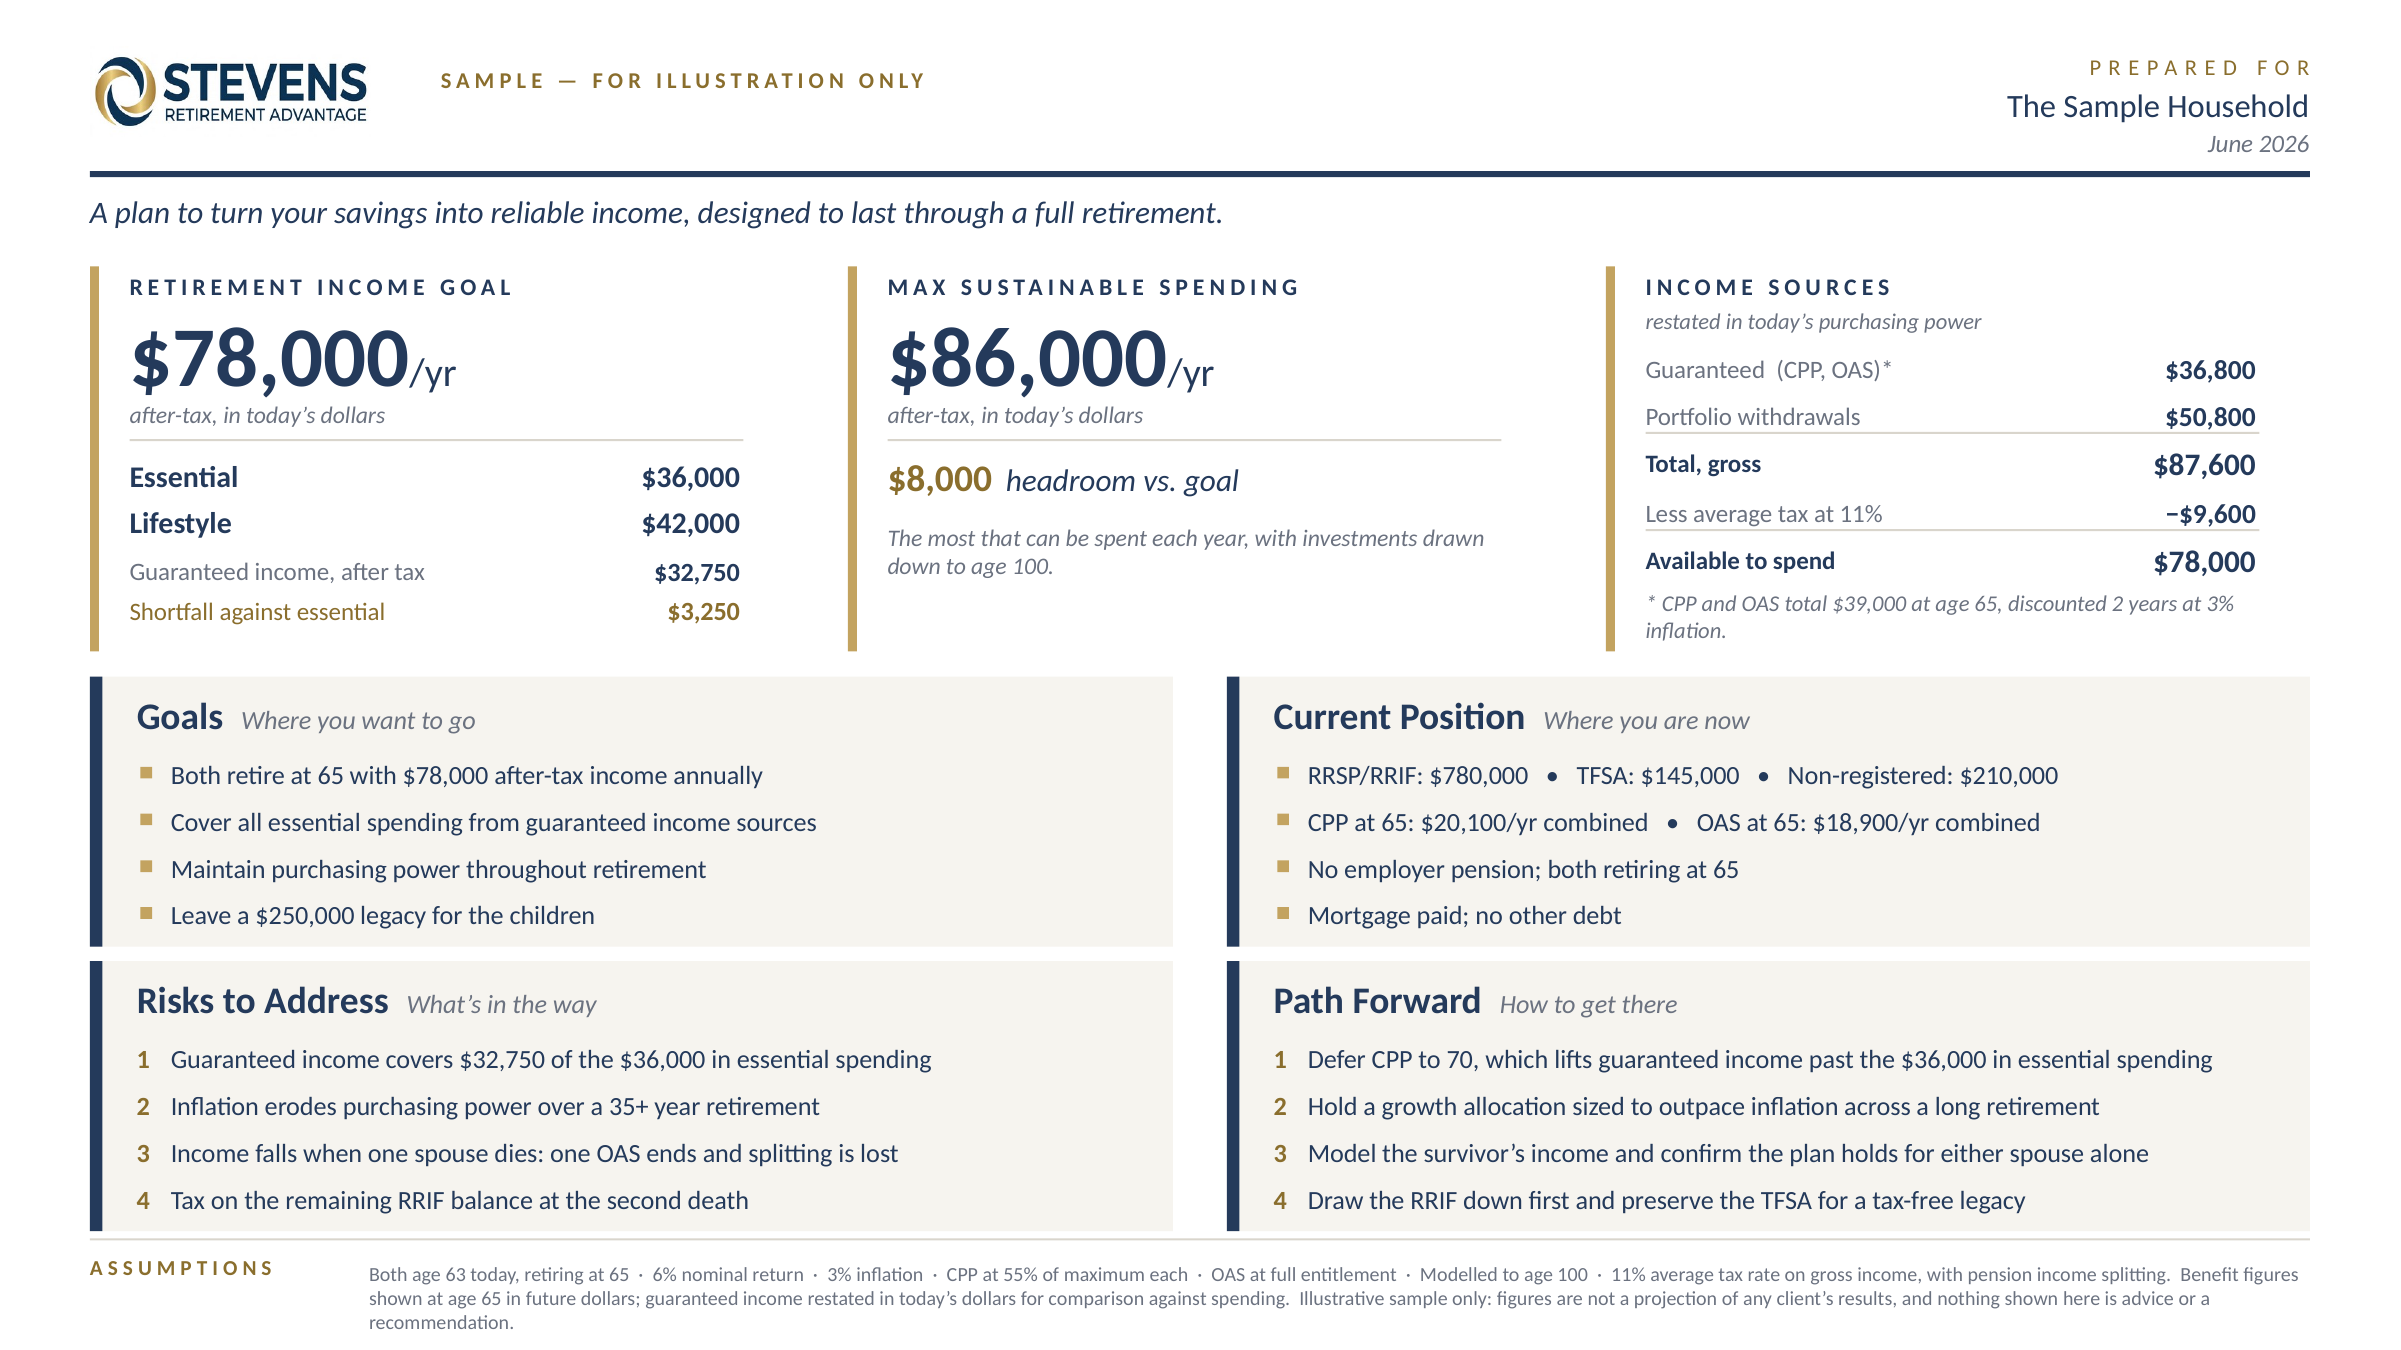
A sample plan, prepared for an illustrative household. Figures are illustrative only and are not a projection of any client's results.
Want to know what each number means?
THE PROCESS
Four steps, from start to finish.
From our initial call to having your completed plan typically takes about three to four weeks, depending on how quickly your financial documents come together.
Step 01
The conversation
A 30-minute introductory call by phone or video. We discuss your current situation, answer your immediate questions, and see if working together makes sense.
Step 02
The full picture
If we decide to move forward, you receive a list of documents to gather. We then have a deeper conversation focused entirely on what you want your retirement to look like, how you plan to spend your time, and what that lifestyle will cost.
Step 03
The modelling
Behind the scenes, different scenarios, tax strategies, and withdrawal sequences are tested against each other to find the optimal strategy for your situation. Nothing is needed from you during this stage.
Step 04
The plan
We meet again, in person or by video, to review your completed Advantage Plan together. You learn the reasoning behind every recommendation and get clarity to your questions before moving forward.
AFTER THE PLAN
The plan provides a roadmap. Execution delivers the results.
Creating a plan gives you a clear starting point, but carrying it out through retirement requires ongoing decisions as your life evolves. Once your plan is complete, you can put it into action on your own, or have it managed on your behalf. There is no cost for the initial planning work. A simple advisory fee only applies if you choose ongoing management, which includes:
Administration handled
Your accounts are consolidated into one place, so the paperwork and transactions are taken off your plate. Cash flow is structured to arrive in your bank account on a regular schedule, drawn from the right accounts in the right order, with tax withholdings managed for you so your income feels as simple as the paycheque it replaces.
Simple, low-cost investing
Portfolios are built using low-cost, globally diversified investments with transparent fees. There is no stock picking and no market timing. When markets move, the strategy holds rather than reacting to short-term headlines.
Clarity through changing times
When your personal goals shift or the rules change, your financial plan is adjusted to reflect your new reality. You also have somewhere to turn when online advice, social media trends, or AI answers make you wonder what actually applies to you. That way the decisions you make are based on your own situation rather than generic commentary.
One relationship for life
Working with a trusted advisor gives you a single point of contact through every stage of life. It also means continuity for both partners, so if one of you is ever on your own, the transition is guided by someone who already knows your story and can take care of the details ahead.
Above $5,000,000 the slider stops, but the figures below still reflect the amount you typed.
Your all-in cost
Per year
That covers the advisory fee, HST, and the cost of the investments themselves. Nothing is added beyond it.
See the full breakdown
| Cost | Rate | Per year |
|---|---|---|
| Advisory feeFor planning and investment management, charged monthly to your accounts | 0.88% | $17,500 |
| HST on the advisory feeCharged with the advisory fee | 0.11% | $2,275 |
| Portfolio costsCharged inside the funds, not billed to you | 0.35% | $7,000 |
| Your all-in cost | 1.34% | $26,775 |
Advisory fees are tiered and billed on assets under management: 1.00% on the first $1,000,000, 0.75% from $1,000,000 to $3,000,000, and 0.50% above $3,000,000. The advisory fee and HST are calculated and charged to your accounts monthly. Portfolio costs are charged by the fund managers within the funds themselves and are reflected in returns rather than billed to you. They vary by the investments selected. Figures shown are an illustrative estimate. Your exact costs are disclosed in writing before any account is opened.
WHAT YOU WOULD PAY
See your own number.
Enter your portfolio size and you’ll see the full annual cost, with nothing left out.
COMMON QUESTIONS
Answers before you get in touch.
What if I already have an advisor?
Most people who get in touch often do. The question is not whether an advisor exists, but whether anyone has clearly calculated what you can safely spend in retirement. That is worth finding out either way.
Is there an account minimum?
There is no set account minimum. Whether working together makes sense depends on the complexity of your situation and whether a dedicated retirement strategy makes a real difference for you. That is what the initial conversation is designed to determine.
Do you need to manage all of my investments?
Yes, for your personal investment accounts. Managing lifetime taxes and sequencing withdrawals requires full visibility across your RRSPs, LIRAs, TFSAs, and taxable accounts. Workplace pensions and group plans remain where they are until you leave, and everyday banking stays right where it is.
Does my spouse need to be involved?
Yes. These decisions affect both partners, and a plan built around one person tends to come apart when circumstances change. Involving both partners also means that if one person is eventually on their own, they are not meeting an advisor for the first time during a difficult transition.
Who actually holds my money?
Investment accounts are held securely in your name with Investia Financial Services.
What if something happens to you?
The practice operates within a network of experienced advisors under the same firm. If your advisor is ever unable to look after your accounts, another advisor within that network steps in to oversee the relationship. Your investments, plan and account holdings remain completely intact and unchanged.
How often do we meet?
Regular meetings happen twice a year. Beyond those scheduled check-ins, you can set up a conversation whenever questions arise or something requires attention.
What if I decide to leave?
There are no fees to transfer out, and nothing used is proprietary. In most cases, investments can move to another institution exactly as they are, without being sold or triggering unnecessary taxes. You are never locked in.
Ready to get started?
Schedule a 30-minute call to explore whether this is the right fit for you.